Futures Market Analysis & Outlook
Week of February 9-16, 2026
Executive Summary
The futures market enters the second week of February 2026 with cautious optimism following extreme volatility in late January and early February. Major equity indices have recovered from a sharp selloff, with the Dow Jones crossing 50,000 for the first time. However, commodities markets—particularly precious metals—experienced historic volatility that reshaped positioning and sentiment across the board.
1. Equity Index Futures - Current Status
Weekend Positioning (Sunday, February 9, 2026)
Market Performance:
- Dow Jones Futures (YMH26): Down 37 points (-0.1% to -0.12%)
- S&P 500 Futures (ES=F): Down 0.15% to 0.2%
- Nasdaq 100 Futures (NQ=F): Down 0.3% to 0.5%
Recent Context:
- The Dow surged 1,232 points (+2.52%) on Friday, February 6, closing above 50,000 for the first time in history
- This followed a turbulent week where tech stocks and cryptocurrencies experienced significant selloffs
- The Nasdaq posted its fourth consecutive weekly loss despite Friday's rally
- Small-cap Russell 2000 outperformed with +2.17% weekly gain
Key Market Drivers This Week
Economic Data Calendar:
-
Wednesday, February 11: January Jobs Report (delayed from Feb 6)
- Expected: 60,000 jobs added (vs. 50,000 in December)
- Unemployment rate forecast: 4.4% (unchanged)
-
Friday, February 13: January Consumer Price Index (CPI)
- Expected: +0.29% monthly, +2.5% annually
- Still above Fed's 2% target but improving from December
-
Tuesday: December Retail Sales Report
Corporate Earnings:
- Coca-Cola, Ford Motor, McDonald's, Robinhood, Coinbase, On Semiconductor scheduled this week
2. Commodities Futures - Extreme Volatility Analysis
Precious Metals: Historic Correction
Gold Futures:
- Current Level: ~$4,950-$5,050 per ounce (recovering)
- Peak (Jan 26): Hit record highs near $5,600
- Crash (Feb 6): Fell 9%+ in single day - worst since 1983
- Weekend Recovery: Up 1.5-3.5% on Friday, stabilizing above $4,900
Silver Futures:
- Current Level: ~$79-$86 per ounce
- Peak: $130+ in late January (after 120% surge in 2025)
- Crash (Feb 6): Plunged 31-34% - worst single-day drop since 1980
- Key Support: Testing $72-$76 breakout zone
Market Analysis: The precious metals collapse was triggered by:
- Kevin Warsh nomination as Fed Chair successor (hawkish perception)
- CME margin requirement increases due to extreme volatility
- Chinese speculative capital withdrawal ahead of Lunar New Year (Feb 16-23)
- Forced liquidation of leveraged positions
- Disconnect between paper markets and physical fundamentals
2026 Forecasts (Revised):
- Gold: Major banks targeting $4,500-$5,000 average
- Macquarie Q1 target: $75 (up from $55)
- Full year average: $62 (up from $57)
- Silver: Banks forecasting $56-$88 range
- Structural supply deficit continues (5th consecutive year)
- AI and solar demand providing floor support
Energy Futures
WTI Crude Oil:
- Current: ~$62-$64 per barrel
- Trend: Down 5.4% on Monday, February 2
- 2026 Average Forecast: $59 per barrel
- Bearish Factors:
- Non-OPEC supply growing 3x faster than demand
- OPEC outlook shifted from deficit to balance
- US commercial inventories near 2014 lows
- Strategic Petroleum Reserve down 33% since 2020
Positioning Insight:
- Net long WTI futures at lowest level since before 2014
- Money managers least prepared for oil price uptick in over a decade
- Potential contrarian bullish signal despite weak fundamentals
Brent Crude:
- Current: ~$67-$68 per barrel
- Bear case: JP Morgan warns of potential drop to low $30s if supply surge continues
3. Market Sentiment & Positioning
Key Observations from CFTC Data
Precious Metals:
- Large speculators and managed funds NOT chasing gold/silver higher despite record prices
- Hesitation suggests smart money sees risks
- Silver net-long exposure declining even as prices rallied
Copper:
- Recovered 25% loss from August
- Positioning showing early signs of fatigue
- Bulls should exercise caution at current levels
WTI Crude:
- Managed funds flipped to net-long (first time in months)
- Large speculators remain cautious - least bullish in 15+ years
- Divergence could signal sentiment extreme
Volatility Indicators
Tech Sector:
- Continued debate over AI disruption risk to legacy software
- "Magnificent Seven" earnings showing mixed results
- Alphabet's $185B capex guidance spooked investors
- Nvidia rallied 8% on Friday, leading recovery
Crypto Correlation:
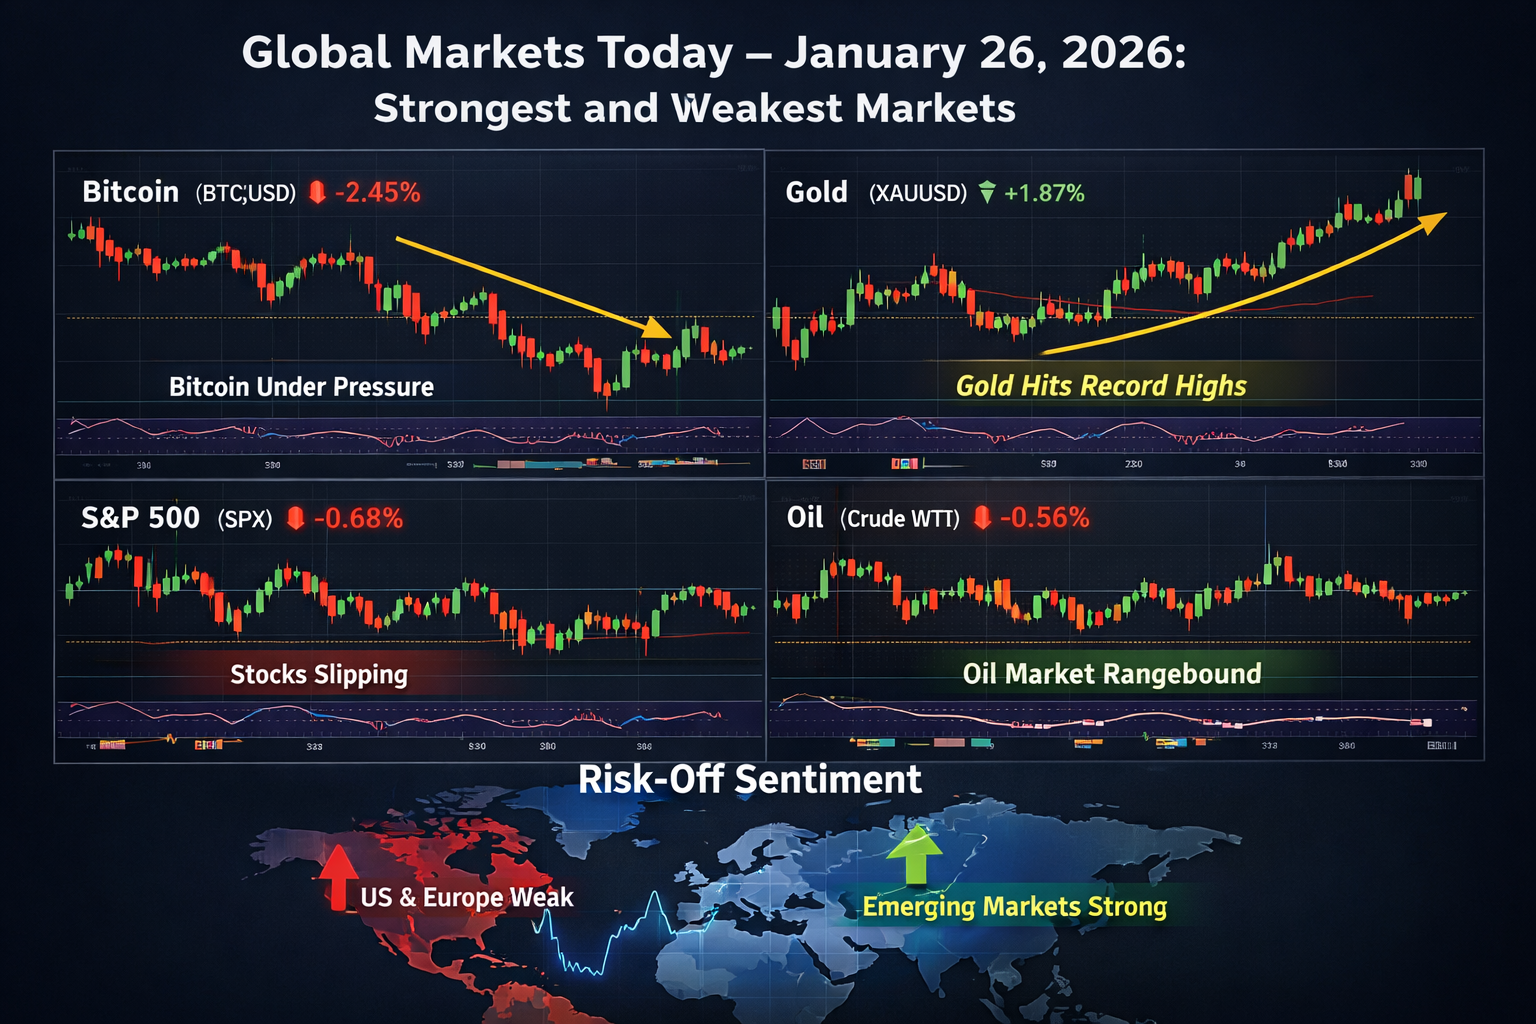
- Bitcoin dropped below $70,000 (from $80,000 last week)
- Strategy Inc (MSTR) down 7% in premarket, at 52-week lows
- Risk-off sentiment impacting digital assets
4. Global Market Factors
Asia-Pacific
Japan:
- Nikkei 225 surged 4%+ to cross 56,000 (new record)
- Topix hit all-time high (+2.27%)
- Driver: PM Sanae Takaichi won landslide election with 2/3 supermajority
- 10-year JGB yields rose to 2.274%
China:
- Reports of urging banks to reduce US Treasury holdings
- Concerns over concentration risks and market volatility
- Lunar New Year (Feb 16-23) expected to reduce speculative flows
- Continued central bank gold purchases (15th consecutive month in January)
Europe
Bond Markets:
- US 10-year Treasury yield: 4.23% (+2 basis points)
- Chinese guidance on US debt holdings creating uncertainty
- Dollar dipped 0.2% against most currencies
5. Weekend Technical Analysis
Equity Index Patterns
S&P 500:
- Trading near 6,920-6,940 range
- Down 0.7% year-to-date
- Support: 6,800 | Resistance: 7,000
- Broadening out beyond tech stocks (healthy rotation)
Dow Jones:
- Historic 50,000 level now support
- Strong momentum from transportation and industrial stocks
- Airlines, FedEx posting new highs
- Support: 49,500 | Resistance: 50,500
Nasdaq Composite:
- Most vulnerable of the three indices
- Down 0.9% year-to-date
- Four consecutive weekly losses
- Tech concentration risk remains concern
Commodity Chart Patterns
Gold (XAU/USD):
- Trading in "Megaphone" or "Broadening Wedge" pattern
- High uncertainty, bulls vs bears battle
- Rejected from upper resistance near $5,600
- Re-entering toward midpoint support
- Key levels: Support $4,640-$4,765 | Resistance $5,200-$5,400
Silver:
- Testing critical support $72-$76 (December breakout level)
- Current: $86.50 | 100-day SMA resistance: $96
- Decision zone - break below $72 very bearish
- Hold above $76 could signal recovery
6. Future Weekend Possibilities & Scenarios
Bullish Scenario (40% probability)
Triggers:
- Better-than-expected jobs report (70K+ jobs)
- CPI comes in below 2.5% YoY
- Corporate earnings exceed lowered expectations
- Stabilization in precious metals attracts dip-buyers
Expected Outcomes:
- Dow extends above 50,500
- S&P 500 breaks 7,000
- Gold recovers to $5,100-$5,200
- Silver bounces to $90-$95
- Tech stocks regain leadership
Bearish Scenario (35% probability)
Triggers:
- Weak jobs data (below 50K)
- CPI remains sticky above 2.6%
- Chinese liquidation of US assets accelerates
- Precious metals break key support levels
- Corporate earnings disappoint
Expected Outcomes:
- S&P 500 tests 6,700
- Dow pulls back to 48,500-49,000
- Gold breaks below $4,640 to $4,400
- Silver crashes to $65-$70
- Flight to cash/short-term Treasuries
Consolidation Scenario (25% probability)
Triggers:
- Mixed economic data
- Lunar New Year reduces Asian volume (Feb 16-23)
- Investors await Fed clarity on Warsh timeline
- Earnings season winds down
Expected Outcomes:
- Equity indices trade sideways in tight ranges
- Gold consolidates $4,800-$5,100
- Silver ranges $75-$88
- Low volume, compressed volatility
- Building energy for post-Presidents Day move
7. Key Risks & Catalysts
Upside Catalysts
- Fed Pivot Signals: San Francisco Fed President Daly suggested 1-2 cuts may be necessary
- China Gold Buying: 15 consecutive months of central bank purchases
- Labor Market Softening: US job cuts hit 108.4K in January (highest since 2009)
- Physical Demand: Gold/silver physical premiums could create buying opportunity
- Sentiment Extremes: Oil positioning at historic lows could trigger squeeze
Downside Risks
- Fed Independence Concerns: Warsh nomination uncertainty
- Geopolitical Tensions: US-Iran talks could fail, military escalation
- Tech Bubble Fears: AI spending at $185B+ raising sustainability questions
- Liquidity Drain: Chinese New Year reduces market depth Feb 16-23
- Margin Calls: Further precious metals volatility could trigger cascading liquidations
- Trump Tariff Threats: Greenland, NATO countries, trade tensions
8. Sector-Specific Outlook
Equity Sectors
Outperformers:
- Transportation (Dow Jones Transportation Average at all-time high)
- Airlines (United +5%, Delta +5%, American +4%)
- Industrials (3M +4.5%, Caterpillar +7%)
- Semiconductors (Nvidia +8%, Broadcom +1%)
Underperformers:
- Software stocks (legacy concerns over AI disruption)
- Cryptocurrency-related equities (Coinbase, MSTR under pressure)
- Consumer discretionary (Alphabet -0.5% despite earnings beat)
Commodity Sectors
Strongest Fundamentals:
- Silver (structural deficit, AI/solar demand)
- Copper (recovering but watch positioning)
- Platinum (down 35% from January peak, potential value at $2,250)
Weakest Fundamentals:
- WTI/Brent crude (oversupply dynamics)
- Natural Gas (seasonal weakness)
- Agricultural commodities (mixed)
9. Trading Recommendations
Short-Term (This Week)
Conservative Approach:
- Reduce position sizes ahead of major data releases
- Use options for hedging rather than directional bets
- Avoid chasing Friday's rally in equities
- Wait for precious metals to establish clear support
Aggressive Approach:
- Small long positions in oversold commodities (oil, silver)
- Tech dip-buying if Nasdaq futures fall another 1-2%
- Short-dated call spreads on Dow ahead of 50,000 retest
- Gold put spreads if rally fails at $5,100
Medium-Term (February-March)
Key Themes:
- Rotation Continues: Small caps, transports, value over mega-cap tech
- Metals Recovery: Physical demand for gold/silver at lower prices
- Energy Bounce: Contrarian oil positioning could pay off
- Fed Watching: Warsh confirmation timeline crucial for bonds
Positioning:
- Diversify away from concentrated tech exposure
- Add commodity exposure on dips (5-10% allocation)
- Consider inflation hedges despite CPI improvement
- Monitor copper as leading economic indicator
10. Weekend Summary & Monday Outlook
Current State (Sunday Evening, Feb 9)
Market Mood: Cautiously optimistic but nervous
- Futures pointing to modest Monday losses after Friday's surge
- Japan election providing tailwind to Asian markets
- China Treasury guidance creating headwind to bonds
- Precious metals recovering but fragile
Monday Open Expectations
Most Likely Scenario:
- Modest pullback (0.1-0.3%) across major indices
- Profit-taking after Dow 50K milestone
- Positioning ahead of retail sales (Tuesday) and jobs (Wednesday)
- Gold tests $5,000-$5,100 resistance
- Oil continues rangebound $62-$65
What Could Change the Script:
- Geopolitical news (Iran, Russia, China)
- Surprise corporate announcements
- Fed speaker comments
- Precious metals volatility resume
Conclusion
The futures market weekend of February 8-9, 2026 represents a critical inflection point. Equity markets have shown resilience with the Dow breaking 50,000, but underlying fragility persists in commodities, particularly precious metals that experienced historic volatility.
The week ahead is data-heavy with delayed jobs and inflation reports that could reshape Fed expectations and market direction. Japan's political stability offers support while Chinese positioning on US assets creates uncertainty.
Key Takeaways:
- Equity bull market intact but rotation away from mega-cap tech underway
- Precious metals volatility extreme but fundamentals remain supportive long-term
- Energy markets positioning at extremes suggesting potential reversal
- Economic data this week will be critical for February trajectory
- Chinese Lunar New Year (Feb 16-23) could reduce liquidity and amplify moves
Recommended Stance: Cautious with reduced leverage, diversified positioning, and heightened attention to risk management given recent volatility extremes.
Report Generated: February 9, 2026 Next Update: February 16, 2026 (Post-Jobs & Pre-CPI)
Data Sources & References
- CME Group - Futures Market Data
- CNBC Markets - Live Updates & Analysis
- Bloomberg - Financial Markets News
- Trading Economics - Economic Indicators
- Fortune - Commodities Analysis
- CFTC - Commitments of Traders Reports
- Reuters - Global Markets Coverage
- MarketWatch - Stock Market Data
- World Gold Council - Gold Market Intelligence
- Federal Reserve Economic Data (FRED)
Disclaimer: This report is for informational purposes only and does not constitute financial advice. Always conduct your own research and consult with financial professionals before making investment decisions.